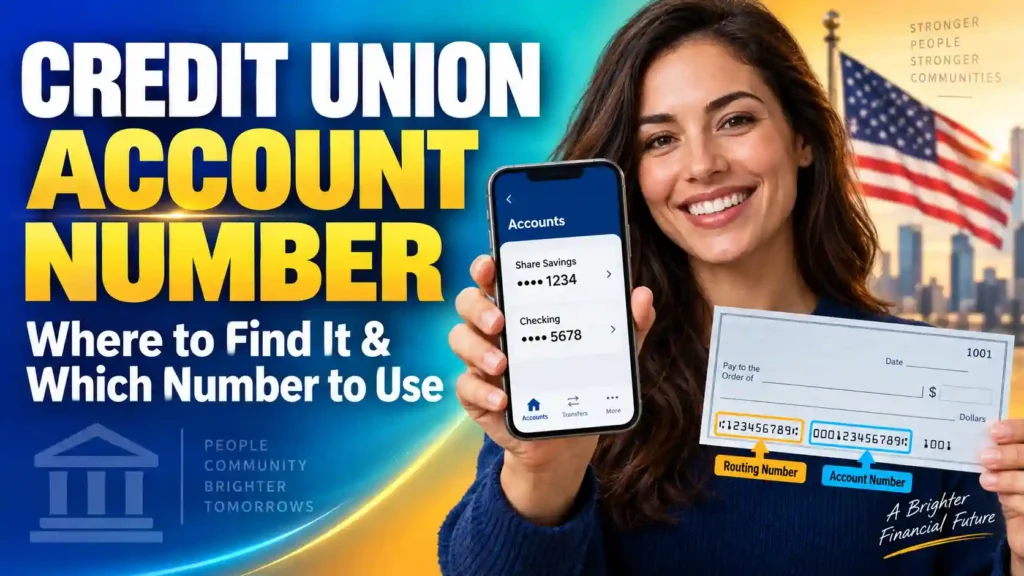
You are setting up direct deposit, connecting another bank or paying a bill when a simple form suddenly becomes confusing. It asks for your credit union account number, but your app shows a member number, share ID, suffix, routing number and possibly a separate MICR number.
Which one should you enter?
Choosing the wrong number can delay your paycheck, reject a transfer or send money into the wrong subaccount. The confusion is understandable because credit unions do not all organize account numbers in the same way.
Some use your member number as part of the account number. Others add a share ID, suffix, prefix or leading zeros. Your checking account may even have a separate number created specifically for ACH transactions and checks.
Here is the short answer:
A credit union account number identifies a specific checking, savings or loan account. Find the complete number in online banking, your mobile app, a current statement, an official direct-deposit form or at the bottom of a check. Do not assume your member number alone is the correct number for ACH transfers.
Your member number may form part of your account number, but the two are not always interchangeable. For direct deposits and external transfers, use the complete number labeled “account number,” “ACH number,” “MICR number” or “direct-deposit account number.”
Table of Contents
What Is a Credit Union Account Number?
A credit union account number is a unique series of digits that identifies one of your financial accounts.
It may identify your:
- Checking account
- Primary savings account
- Secondary savings account
- Money market account
- Certificate account
- Personal loan
- Auto loan
- Mortgage
- Credit card account
- Line of credit
Unlike a routing number, which identifies the credit union, an account number directs the transaction to your specific account.
However, credit unions often operate with a membership-based structure. Instead of creating one unrelated number for every financial product, a credit union may organize several products under one central member number.
It can then use prefixes, suffixes or share IDs to distinguish checking from savings, loans and other accounts.
Credit Union Account Number vs Member Number
A member number identifies your overall relationship with the credit union. An account number identifies one particular financial account.
That difference is easy to miss because some credit unions casually use “member number” and “account number” as if they mean the same thing. At other institutions, they are completely different.
| Number | What it identifies | Common use |
|---|---|---|
| Member number | Your membership relationship | Member service, branch transactions and online enrollment |
| Account number | One specific account | Direct deposit, ACH transfers and automatic payments |
| Share ID | A deposit subaccount | Identifying checking, savings or another share |
| Account suffix | An account or loan under the membership | Internal and external transaction identification |
| MICR number | A transaction-ready checking account | Checks, ACH credits and electronic withdrawals |
| Routing number | The credit union | Directing the transaction to the institution |
| Debit card number | Your payment card | Purchases and ATM transactions |
For example, imagine that a fictional member has the following information:
| Identifier | Fictional example | What it means |
|---|---|---|
| Member number | 1234567 | Identifies the member |
| Checking suffix | 10 | Identifies the checking share |
| Savings suffix | 00 | Identifies the primary savings share |
| ACH checking number | 00123456710 | Complete number used for outside transfers |
| Routing number | 123456789 | Identifies the fictional credit union |
| Debit card number | 4444 5555 6666 7777 | Identifies the card, not the account |
These numbers are illustrations only. Do not use them for a real transaction.
The example shows why entering only 1234567 may not work. An external payment system could require the complete checking number, including the additional digits.
What Is a Credit Union Member Number?
A member number is assigned when you join a credit union. It helps the institution identify your membership and group your products under one relationship.
You may need your member number when:
- Contacting member services
- Visiting a shared branch
- Enrolling in online banking
- Voting in a credit union election
- Discussing your overall membership
- Accessing telephone banking
- Completing certain internal forms
Your member number may appear on your welcome letter, membership card or statement. Nevertheless, it is not automatically the right number for payroll, tax refunds or external ACH transfers.
Can the Member Number Also Be an Account Number?
Yes, but the rule depends on the credit union.
At one institution, the member number may also identify the primary savings account. At another, it must be combined with a suffix. A third may issue a separate ACH account number that looks nothing like the membership number.
That is why a universal instruction such as “add 00 to your member number” is dangerous. It might work at one credit union and fail completely at another.
What Is a Share Account at a Credit Union?
Credit unions are member-owned financial cooperatives. When you deposit the required amount into your primary savings account, that deposit represents your share of ownership in the institution.
Consequently, credit unions often call deposit accounts “share accounts.”
Common examples include:
- Share savings
- Share draft checking
- Secondary share savings
- Holiday share account
- Money market share
- Share certificate
A share draft account is essentially a credit union checking account. “Draft” refers to payments drawn against the account, including checks and electronic withdrawals.
What Is a Share ID?
A share ID is a short code used to distinguish one share account from another.
For example, one credit union could use:
- 00 for primary savings
- 10 for checking
- 20 for secondary savings
- 30 for holiday savings
Another credit union may use completely different codes. There is no nationwide suffix system that every institution follows.
The share ID may appear:
- Before the member number
- After the member number
- After a dash
- As a separate field
- Inside a longer ACH account number
- Only in the credit union’s internal system
Should You Include the Share ID?
Include it only when the credit union’s instructions require it.
If your account appears as 1234567-10, do not automatically enter 123456710 into an ACH form. The correct electronic account number might contain leading zeros, an additional prefix or a separate MICR sequence.
Look for the complete number specifically labeled for direct deposit or ACH transactions.
What Is an Account Suffix?
An account suffix is a short code that identifies an individual account beneath your main membership.
A credit union may use suffixes to distinguish:
- Checking
- Primary savings
- Secondary savings
- Money market
- Certificate
- Auto loan
- Personal loan
- Credit card
- Mortgage
Suffixes are not standardized. The same suffix can mean checking at one credit union and something different at another.
Never copy the formatting instructions of another institution, even if its membership numbers look similar.
What Is a MICR Account Number?
MICR means Magnetic Ink Character Recognition. It refers to the machine-readable numbers and symbols printed along the bottom of a check.
The MICR line generally contains:
- Routing number
- Checking account number
- Check number
At many credit unions, the MICR account number is the complete transaction-ready checking number used for paper checks and ACH processing. It may be longer than your member number because it includes additional digits identifying the checking share.
A MICR number may be used for:
- Payroll direct deposit
- Tax refunds
- Government benefits
- Automatic bill payments
- ACH transfers
- Electronic withdrawals
- Check clearing
If online banking displays both a member number and a checking MICR number, the MICR or ACH number is generally the safer choice for an external checking transaction—unless your credit union instructs you differently.
Where to Find Your Credit Union Account Number
The best source is the account itself. Do not try to reconstruct the number from memory.
Find It in Online Banking
Sign in through your credit union’s official website and select the exact checking or savings account.
Look for an option labeled:
- Account details
- Account information
- Show full account number
- Direct deposit
- ACH information
- MICR number
- Routing and account numbers
- Manage account
Make sure you are viewing the individual account—not merely your membership profile.
Find It in the Mobile App
Open the official app and select the account you want to use. Tap “Details,” “Information,” “Show account number” or a similar option.
For security, the app may display only the last four digits until you verify your identity.
Copy the number directly rather than typing it from memory. A missing zero can cause the transaction to fail.
Find It on a Check
Most personal checks show three groups of numbers along the bottom.
The typical order is:
- Routing number
- Account number
- Check number
The routing number is usually the first nine-digit group on the left. The checking account number commonly appears next. The check number is often the shorter group and should match the number printed in the upper-right corner.
However, not every check follows the same arrangement. Some business checks place the check number before the account number.
If you cannot confidently identify the account number, ask your credit union instead of guessing.
Find It on a Statement
The complete account number may appear beside the balance and transaction history on a paper or electronic statement.
Be careful: the number at the top of the statement may be your member number, while separate account numbers appear inside the statement.
Some institutions mask most digits for privacy. In that case, use digital banking or request an official account-verification letter.
Find It on a Direct-Deposit Form
Many credit unions provide a prefilled or downloadable direct-deposit form.
It may include:
- Member’s name
- Credit union name
- Routing number
- Complete account number
- Checking or savings designation
- Deposit instructions
This form is often the safest option for payroll because it provides the number in the exact format the credit union expects.
Call Member Services
Call the number on the back of your debit card or inside the official app.
Use precise language:
“I need the complete ACH account number for direct deposit into my checking account. Should I include any suffixes or leading zeros?”
That question is better than simply asking for your account number. It tells the representative exactly which transaction you are preparing.
Which Number Should You Use for Direct Deposit?
For direct deposit, use the complete ACH account number for the specific account receiving the money.
You will usually need:
- Credit union routing number
- ACH account number
- Account type
- Name on the account
- Deposit amount or percentage
Do not use:
- Debit card number
- Check number
- Loan number
- Member number unless confirmed
- A shortened version of the account number
- Another member’s formatting example
Direct Deposit Into Checking
Use the complete checking ACH or MICR number displayed in your account details.
If your employer asks for a voided check, confirm that the number on the check remains current.
Direct Deposit Into Savings
Savings accounts may not have checks or MICR lines. Use the account number listed under the savings account’s direct-deposit details.
The savings account number might be your member number, your member number plus a share ID or a completely separate number.
Split Direct Deposit
Some employers let you divide your pay between checking and savings.
Each account may require:
- The same credit union routing number
- A different account number
- Its correct checking or savings designation
- A fixed amount or percentage
Confirm both account numbers separately.
Which Number Should You Use for an ACH Transfer?
Use the complete external ACH account number assigned to the receiving or funding account.
ACH transfers include:
- Bank-to-bank transfers
- Automatic loan payments
- Utility payments
- Insurance premiums
- Subscription payments
- Payroll deposits
- Tax refunds
Some credit unions show an abbreviated number for internal transfers and a longer number for outside ACH transactions. Use the external ACH number.
If the other bank rejects the account number, do not repeatedly add or remove suffixes. Ask your credit union to confirm the required format.
Which Number Should You Use for a Wire Transfer?
A wire transfer may require different information from an ACH payment.
Your credit union might receive wires directly or through a larger correspondent institution. Therefore, incoming instructions may request:
- Receiving bank
- Intermediary bank
- Wire routing number
- Credit union name
- Credit union address
- Member’s name
- Member number
- Final credit account number
- Reference or “for further credit” instructions
Obtain current instructions directly from the credit union before sending a wire.
Wire transfers can be expensive and difficult to reverse. Never rely solely on instructions received through an unexpected email, text message or changed invoice. Verify them through a trusted phone number.
Which Number Should You Use for a Tax Refund?
Use the complete ACH number for the checking or savings account where you want the refund deposited.
Before submitting your tax return, verify:
- All digits are correct
- Leading zeros are included
- The routing number has nine digits
- Checking or savings is selected properly
- The account accepts ACH deposits
- Your name is associated with the account
An incorrect number can delay the refund. If the details identify another valid account, recovering the money may be difficult.
Which Number Should You Use for Social Security?
Use the direct-deposit account number for the eligible checking or savings account receiving the benefit.
Do not use a debit card, loan or general membership number unless the credit union confirms that it is the correct ACH identifier.
If you change accounts, keep the old account open until the updated deposit information has taken effect and you confirm where the next payment will arrive.
Which Number Should You Use for a Loan Payment?
A loan number identifies money you owe, not a checking or savings balance.
If you are paying a credit union loan from an outside bank, the required number could be:
- Loan account number
- Member number plus loan suffix
- Special ACH payment number
- Payment reference
- Checking account number followed by an internal transfer
Do not send money directly to a loan account unless the credit union confirms that the account accepts external ACH credits.
Which Number Should You Use for a Payment App?
When connecting a credit union to a payment app, use the checking or savings account’s external ACH number.
Some apps verify ownership by sending small trial deposits. Others may ask you to sign in through a secure bank-linking service.
If the app rejects your account:
- Confirm the routing number.
- Confirm the account type.
- Locate the external ACH number.
- Include required leading zeros.
- Check whether the app supports your credit union.
- Contact member services before changing the format.
Account-Number Formats at Popular Credit Unions
Every credit union has its own system. The following examples show why you should follow institution-specific instructions.
Navy Federal Credit Union
Navy Federal assigns members an Access Number that identifies their overall membership. That number is not automatically the checking or savings account number required for every external transaction.
For direct deposit or ACH transfers, open the relevant account and obtain its complete account number. Do not substitute your debit card number or assume the Access Number alone is sufficient.
Navy Federal’s commonly used routing number is 256074974. For a full explanation, review the Navy Federal account number vs Access Number before submitting external payment details.
Alliant Credit Union
Alliant members setting up direct deposit need the routing number, the checking or savings account number and the correct account type.
Alliant checking account numbers can contain 14 digits. Therefore, a shorter member identifier should not be substituted for the complete checking number shown in the account.
The commonly used Alliant routing number is 271081528.
PenFed Credit Union
PenFed members can locate individual account numbers by signing in and opening the relevant account information or direct-deposit management section.
The member number and individual account number should not be treated as interchangeable without confirmation.
PenFed’s commonly used routing number is 256078446.
State Employees’ Credit Union
Do not assume every institution called State Employees’ Credit Union follows the same numbering system. Several credit unions use similar names in different states.
Open the specific checking or savings account and use the complete electronic account number displayed there.
North Carolina State Employees’ Credit Union commonly uses routing number 253177049, but members should still verify their individual account numbers.
Delta Community Credit Union
At some credit unions, including Delta Community, the member number may also function as the primary savings account number. However, checking and additional savings accounts may require different numbers or share IDs.
This is exactly why you cannot apply one credit union’s account-number rule to another.
Service Credit Union
Service Credit Union members can view individual account numbers by opening the relevant account in digital banking and revealing its full details.
Use the individual account number for direct deposits and external transfers, rather than assuming the general member number is sufficient.
Credit Union Account Number vs Routing Number
Your routing and account numbers work together, but they do different jobs.
| Feature | Credit union account number | Routing number |
|---|---|---|
| Identifies | Your specific account | The credit union |
| Length | Varies | Exactly nine digits |
| Unique to you | Usually | No |
| Shared with other members | No | Yes |
| Used for direct deposit | Yes | Yes |
| Publicly searchable | No | Often |
| May contain a suffix | Yes | No |
| Should be protected | Yes | Yes, particularly with other personal details |
The routing number directs the transaction to your credit union. The account number tells the institution which account should receive or provide the money.
If you do not know the institution’s nine-digit code, use a bank and credit union routing numbers list as a starting point, then verify the number in your account.
Credit Union Account Number vs Debit Card Number
Your debit card number is not your checking account number.
A debit card number usually contains 16 digits and identifies the payment card. Your checking account number identifies the deposit account connected to it.
If your debit card expires or is replaced, the card number may change while the checking account number stays the same.
Enter the card number only when the form specifically requests debit card information.
Credit Union Account Number vs Check Number
A check number identifies one individual check. It does not identify your checking account.
On a personal check, the check number often appears:
- In the upper-right corner
- As the final number group along the bottom
Because the check number is usually short, it can be mistaken for an account suffix. Compare it with the number printed at the top before entering anything.
How Long Is a Credit Union Account Number?
There is no standard length.
A credit union account number may contain:
- Six digits
- Seven digits
- Eight digits
- Ten digits
- Twelve digits
- Fourteen digits
- More digits at some institutions
The number may be longer than your member number because it includes:
- Leading zeros
- Share ID
- Account suffix
- Product identifier
- Processing prefix
- MICR formatting
Length alone cannot confirm whether you have the correct number.
Do Leading Zeros Matter?
Yes. Keep every leading zero unless your credit union explicitly tells you to remove it.
For an electronic payment system, 0012345678 and 12345678 can represent different account numbers.
Should You Include Hyphens?
Most ACH forms accept digits only. They may automatically reject spaces, letters or hyphens.
However, removing a hyphen does not necessarily produce the correct number. If the displayed account is 1234567-10, confirm whether the ACH format is 123456710 or a longer number containing additional digits.
Can Account Numbers Contain Letters?
Most U.S. ACH account numbers are entered as digits. A credit union may display letters internally to describe a share or loan, but an external payment form may require a numeric equivalent.
Ask the credit union how to convert or enter the identifier. Do not guess.
Why Is Your Credit Union Account Number Being Rejected?
You Entered the Member Number
The payment system may require the full account-specific ACH or MICR number.
The Share ID Is Missing
Your credit union may require a suffix or share ID to distinguish checking from savings.
You Used the Wrong Share ID
The number may point to a loan, secondary savings or another account instead of checking.
You Removed Leading Zeros
Leading zeros are part of the account number and may be necessary for correct processing.
You Selected the Wrong Account Type
Choosing checking for a savings account—or savings for checking—can cause a verification failure.
You Entered the Debit Card Number
The 16-digit card number is not the checking account’s ACH number.
You Used an Internal Number
A short number used for transfers within the credit union may not work through an outside ACH system.
The Account Does Not Support the Transaction
Some certificate, loan and specialized savings accounts cannot receive external ACH deposits.
The Routing Number Is Incorrect
The account number can be correct while the routing number is wrong. Verify both independently.
The Account Was Recently Opened
New accounts may not appear immediately in third-party verification systems.
The Credit Union Changed Its Processing System
A merger or account conversion can change the required format. Replace saved payment instructions if the credit union provides new details.
What Happens If You Enter the Wrong Account Number?
The Deposit May Be Returned
If the destination account does not exist, the credit union may reject the payment and return it to the sender.
This process can take several business days.
Your Paycheck May Be Delayed
Contact payroll immediately. Your employer may need to issue a replacement payment or wait for the original deposit to return.
Money May Enter the Wrong Subaccount
An incorrect suffix could direct money to savings instead of checking or toward a loan instead of a deposit account.
Money Could Reach Another Member
If the numbers form a valid account belonging to someone else, recovery may be complicated. Contact the sending institution and receiving credit union immediately.
A Bill Payment Could Fail
A failed automatic payment may cause:
- Returned-payment fees
- Late fees
- Service interruption
- Collection activity
- Possible credit damage if the payment becomes seriously overdue
How to Protect Your Credit Union Account Number
Use Secure Forms
Submit banking details through your employer’s verified payroll portal, the credit union’s official app or a secure government or biller website.
Never Share Login Credentials
No one needs your password, debit card PIN or one-time verification code to deposit money into your account.
Be Careful With Changed Wire Instructions
Scammers sometimes intercept payment conversations and replace legitimate wire instructions.
Call the recipient using a trusted phone number before sending a large payment.
Monitor Your Transactions
Enable alerts for:
- External withdrawals
- Large transactions
- New payees
- Password changes
- Low balances
- Failed login attempts
Protect Paper Documents
Store checks, statements and direct-deposit forms securely. Shred them before disposal.
Frequently Asked Questions About Credit Union Account Numbers
Is my member number the same as my account number?
It can be, but it is not always. Confirm the transaction-ready number for the specific account.
Where can I find my credit union account number?
Look in online banking, the mobile app, a current statement, an official direct-deposit form or at the bottom of a check.
Is my account number printed on my debit card?
No. The number on your debit card identifies the card, not the underlying checking account.
Is the account number the same as the routing number?
No. The routing number identifies the credit union. The account number identifies your individual account.
How many digits does a credit union account number have?
The length varies by institution. There is no universal U.S. format.
What is a share account number?
It is the number assigned to a deposit account held by a credit union member.
What is a share ID?
A share ID is a code used to distinguish checking, savings and other subaccounts under the same membership.
Should I add the suffix to my member number?
Only if your credit union specifically instructs you to do so.
What is a MICR number?
It is a machine-readable account identifier used for processing checks and, at many institutions, ACH transactions.
Is the MICR number the same as my member number?
Not necessarily. The MICR number may contain additional digits identifying a specific checking account.
Can I find my account number on a check?
Usually. It commonly appears after the nine-digit routing number along the bottom.
Can I find it on a statement?
Often, although some statements mask part of the number.
What number does an employer need for direct deposit?
Your employer usually needs the routing number, complete ACH account number and account type.
Can I use my member number for direct deposit?
Only when the credit union confirms that it is also the correct ACH account number.
Which number should I use for savings?
Use the complete ACH number displayed for that specific savings share.
Which number should I use for checking?
Use the complete checking account number labeled for ACH, MICR or direct deposit.
Which number should I use for an external transfer?
Use the external ACH account number shown for the account you are linking.
Which number should I use for a wire?
Use the credit union’s current incoming-wire instructions. Do not assume the ACH number is sufficient.
Can checking and savings share a member number?
Yes. They may share the central member number while using different suffixes or complete account numbers.
Why is my account number longer than my member number?
It may contain leading zeros, a processing prefix, share ID or account suffix.
Why is my number different on a check?
The check may display a complete MICR account number while another document shows only your member number.
Can my credit union account number change?
Yes. It may change after fraud, closure, reopening, a merger or account-system conversion.
Is it safe to give my employer my account number?
Yes, when submitting it through a verified direct-deposit process.
Can someone withdraw money with my account and routing numbers?
Those numbers can be used to initiate certain electronic transactions. Protect them and monitor your account for unauthorized activity.
Can someone access online banking with my account number?
An account number alone should not grant access, but criminals may combine it with other stolen information. Never share passwords or verification codes.
Does every account at a credit union accept ACH deposits?
No. Certain certificates, loans and specialized accounts may not accept outside ACH transactions.
What should I do if money was sent to the wrong account?
Contact the sending institution and receiving credit union immediately. Provide the amount, date and transaction confirmation number.
Final Checklist: Use the Right Credit Union Account Number
Before submitting a transaction, confirm that:
- You selected the correct checking, savings or loan account.
- You are using the complete ACH or MICR account number.
- You did not substitute your debit card number.
- You did not assume the member number was enough.
- Required prefixes, suffixes and leading zeros are included.
- The routing number contains nine digits.
- Checking or savings is selected correctly.
- The account accepts the intended transaction.
- Wire instructions were verified separately.
- Every digit was checked before submission.
Credit union account numbers can look unnecessarily complicated, but there is one rule that prevents most mistakes: never construct the number yourself unless your credit union gives you explicit instructions.
Open the exact account, locate the number labeled for ACH or direct deposit and copy it exactly as displayed. That final check takes less than a minute—and can save you days of rejected payments, delayed deposits and recovery calls.

