Have you ever been asked to enter your routing number and account number, then paused because you weren’t completely sure which was which?
You’re certainly not alone.
It’s one of the most common banking questions, and it’s also one of the easiest mistakes to make. Every day, people accidentally swap these two numbers when setting up direct deposits, paying bills, linking bank accounts, or sending money electronically. Sometimes the payment is simply rejected. Other times, it can delay an important transaction and create hours of unnecessary frustration.
Imagine you’re starting a new job.
Your employer asks you to complete a direct deposit form. You confidently enter your account number where the routing number belongs. Payday arrives, but your salary doesn’t.
After contacting your payroll department, you discover the mistake. A simple mix-up between two banking numbers delayed your paycheck by several days.
Fortunately, it’s a mistake that’s easy to avoid once you understand what each number does.
In this guide, you’ll learn the difference between a routing number and an account number, where to find each one, how they work together, and why both are essential for electronic banking. You’ll also discover common mistakes, practical examples, and simple tips to help you complete banking forms with confidence.
By the end of this article, you’ll never confuse these two numbers again.
Table of Contents
Quick Answer
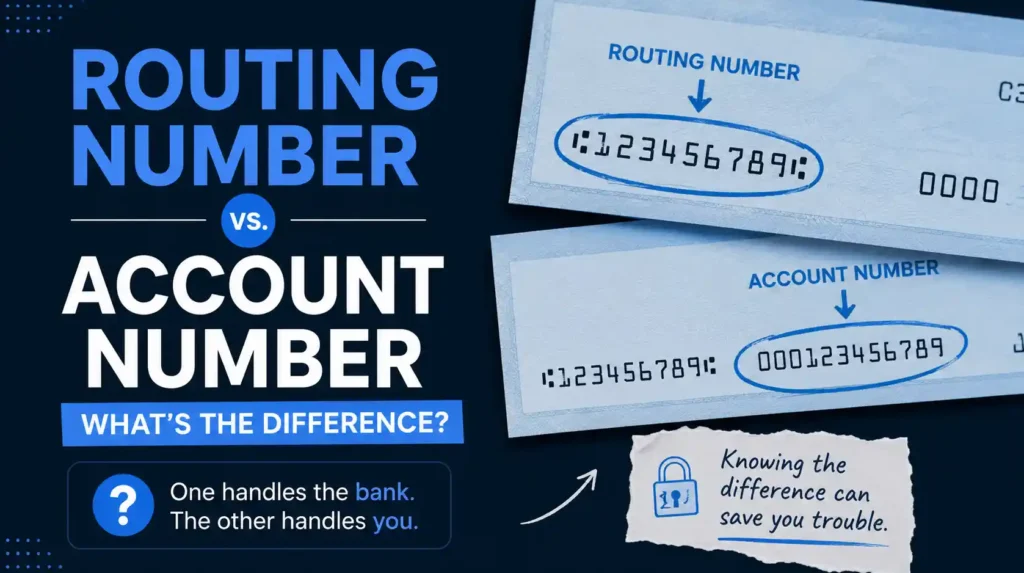
A routing number identifies the financial institution where your account is held, while an account number identifies your individual bank account at that institution.
Think of it this way:
- The routing number tells the banking system which bank should receive the payment.
- The account number tells the bank which customer should receive the money.
Most electronic transactions require both numbers to ensure payments reach the correct destination.
Routing Number vs. Account Number at a Glance
Before we explore each one in detail, here’s a quick comparison.
| Feature | Routing Number | Account Number |
|---|---|---|
| Identifies | The financial institution | Your individual bank account |
| Assigned By | The banking system | Your bank |
| Length | Always 9 digits in the U.S. | Usually 8–17 digits |
| Shared With Others | Yes | No |
| Used For | Directing payments to the correct bank | Identifying the correct customer |
| Changes Often? | Rarely | Usually stays with your account |
Although these numbers often appear together, they serve completely different purposes.
Understanding that difference is the key to avoiding many common banking errors.
What Is a Routing Number?
A routing number is a unique nine-digit code that identifies a financial institution in the United States.
Banks use routing numbers to determine where electronic payments, checks, and other financial transactions should be sent.
Without routing numbers, banks wouldn’t know which financial institution should receive your money.
Routing numbers are commonly used for:
- Direct deposits
- ACH transfers
- Electronic bill payments
- Wire transfers
- Check processing
- Tax refunds
- Government benefit payments
- Payroll deposits
Because routing numbers identify banks rather than customers, thousands—or even millions—of people can share the same routing number.
For example, if two people both bank with the same financial institution in the same region, they may have identical routing numbers while maintaining completely different bank accounts.
Why Is It Called a Routing Number?
The name comes from its purpose.
It literally routes money through the banking system.
Whenever an electronic payment begins its journey, the routing number tells payment networks which financial institution should receive it before the payment reaches the individual customer.
Without this information, banks would have no reliable way to direct billions of electronic transactions every year.
What Is an Account Number?
While the routing number identifies the bank, the account number identifies you.
Your account number is a unique number assigned to your checking or savings account.
No two customers at the same bank should have the same account number.
Think of your account number as your personal address inside the bank.
Once a payment reaches the correct financial institution, the account number tells the bank exactly which customer should receive the funds.
Your account number is commonly used for:
- Receiving direct deposits
- Paying bills
- Sending electronic transfers
- Linking payment apps
- Setting up automatic payments
- Depositing tax refunds
- Receiving government benefits
Unlike routing numbers, account numbers vary in length depending on the financial institution.
Some banks use eight digits.
Others may use twelve, fourteen, or even seventeen digits.
There is no universal standard for account number length.
How Routing Numbers and Account Numbers Work Together
Understanding how these two numbers work together makes banking much easier.
Let’s look at a practical example.
Sarah has a checking account at her local bank.
Her employer asks her to complete a direct deposit form before her first payday.
She provides:
- Her routing number
- Her account number
- Her account type
Here’s what happens behind the scenes.
Step 1: Payroll Is Processed
Sarah’s employer submits payroll through its banking system.
Step 2: The Routing Number Identifies the Bank
The routing number directs the payment to Sarah’s financial institution.
At this stage, the banking network still doesn’t know which customer should receive the money.
It only knows which bank should receive the payment.
Step 3: The Account Number Identifies Sarah
Once the payment reaches the correct bank, the account number tells the bank which customer owns the account.
Step 4: The Funds Are Deposited
Sarah’s salary is deposited into her checking account.
The entire process happens automatically, often without her realizing how both numbers worked together behind the scenes.
One important thing many people overlook is that neither number can do the entire job alone.
A routing number without an account number tells the banking system where to send the money—but not who should receive it.
An account number without a routing number identifies the customer—but not the financial institution where the account is held.
Both are essential for completing most electronic banking transactions.
Where Can You Find Your Routing Number and Account Number?
Knowing the difference between a routing number and an account number is only part of the equation. You also need to know where to find them when completing banking forms or verifying your account information.
Fortunately, banks make both numbers relatively easy to locate.
On a Paper Check
If you have a personal check, you’ll usually find both numbers printed along the bottom using special magnetic ink that allows banks to process checks quickly and accurately.
The numbers normally appear in this order:
| Position on the Check | Number |
|---|---|
| First | Routing Number |
| Second | Account Number |
| Third | Check Number |
The routing number is always the first group of numbers on the left.
Your account number appears immediately after the routing number.
The final group identifies the individual check rather than your bank account.
If you’re ever unsure which number is which, remember this simple rule:
Routing comes first. Account comes second.
Through Online Banking
Most banks display both numbers inside their online banking platforms.
After signing in, navigate to your account details or account information page.
Depending on your bank, you’ll usually see:
- Routing number
- Account number
- Account type
- Available balance
- Direct deposit information
This is one of the safest places to verify your banking information because it comes directly from your financial institution.
Using Your Bank’s Mobile App
If you’re away from your computer, your bank’s mobile app can usually provide the same information.
Many banking apps include a section labeled:
- Account Details
- Account Information
- Direct Deposit Information
From there, you can often view or securely copy both your routing number and account number.
Using your bank’s official app helps reduce the risk of copying incorrect information from unofficial websites.
On Your Bank Statement
Your monthly statement may also include your routing number and account number.
Whether you receive paper statements or electronic statements, reviewing your account information before completing important banking forms is always a good habit.
By Contacting Your Bank
If you still can’t locate your routing number or account number, contact your bank directly.
A customer service representative can verify your banking information and answer questions about which routing number applies to your account.
This is especially important before:
- Setting up direct deposit
- Sending a large payment
- Completing payroll forms
- Authorizing recurring electronic transfers
Why Do You Need Both Numbers?
Many people wonder why banks require two different numbers instead of just one.
The answer becomes clear when you look at how electronic payments move through the banking system.
Think of mailing a package.
Writing only the city isn’t enough.
Writing only the street address isn’t enough either.
You need both.
Banking works the same way.
The routing number identifies the financial institution.
The account number identifies the individual customer.
Together, they ensure that money reaches the right bank and the right account.
Without one of these numbers, the payment usually cannot be completed successfully.
Common Situations Where You’ll Need Both Numbers
Although many people only think about routing numbers when starting a new job, they’re used much more often than that.
You’ll commonly need both numbers when:
Setting Up Direct Deposit
Employers usually request both your routing number and account number before sending your salary electronically.
Providing incorrect information can delay your first paycheck.
Paying Bills Automatically
Utility companies, mortgage lenders, insurance providers, and subscription services often ask for both numbers when you authorize automatic withdrawals.
This allows payments to be processed on schedule without requiring manual payments each month.
Linking Bank Accounts
Many financial apps require both numbers before allowing you to transfer money between accounts.
Examples include:
- PayPal
- Venmo
- Cash App
- Brokerage accounts
- Savings apps
The routing number identifies your bank, while the account number identifies the specific account being linked.
Receiving Tax Refunds
If you choose direct deposit when filing your federal or state tax return, you’ll usually provide:
- Your routing number
- Your account number
- Your account type
Entering incorrect information may delay your refund while the payment is returned or corrected.
Receiving Government Benefits
Programs such as:
- Social Security
- Veterans benefits
- Pension payments
- Unemployment benefits
typically use direct deposit.
Providing accurate banking information helps ensure payments arrive on time.
Common Mistakes People Make
Most banking errors involving routing numbers and account numbers are surprisingly simple.
Here are the mistakes that occur most often.
Entering the Numbers in Reverse
This is probably the most common mistake.
Some people accidentally type their account number where the routing number belongs.
Others enter the routing number twice.
Always review your information carefully before submitting any banking form.
Assuming Every Bank Uses the Same Routing Number
Large financial institutions often have multiple routing numbers.
The routing number associated with your account may depend on:
- The state where the account was opened
- The type of transaction
- Internal bank processing
Never assume another customer at the same bank uses the same routing number you do.
Copying Banking Information From Old Documents
Banks occasionally update routing information following mergers or operational changes.
Before completing an important transaction, verify your routing number using your bank’s official website, online banking account, or mobile app.
Typing Errors
Even one incorrect digit can prevent an electronic payment from reaching its destination.
Before clicking Submit, compare every digit against your official banking records.
Taking less than a minute to review your information can save days of unnecessary delays.
Which Number Should You Keep More Private?
This is another question many people ask.
While neither number should be shared carelessly, your account number generally deserves greater protection.
Here’s why.
A routing number identifies your financial institution and is shared by many customers.
An account number identifies your specific account.
Together, these numbers can sometimes be used to authorize certain types of electronic payments.
For that reason, avoid posting photos of:
- Checks
- Bank statements
- Direct deposit forms
on social media or sending them through unsecured messaging apps.
If you need to provide your banking information, make sure you’re dealing with a trusted organization and using a secure communication method.
One simple habit can significantly reduce your risk of fraud:
Only share your complete banking details when they’re genuinely required and you know exactly who is requesting them.
Routing Number vs. Account Number: Real-Life Examples
Understanding the theory is helpful, but seeing how routing numbers and account numbers are used in everyday situations makes the difference much clearer.
Let’s walk through a few real-world examples.
Example 1: Setting Up Direct Deposit
Emily has just accepted a new job.
Her employer gives her a direct deposit form and asks for:
- Routing number
- Account number
- Account type
Emily enters both numbers correctly.
On payday:
- The routing number directs the payment to her bank.
- The account number tells the bank which account belongs to Emily.
- Her salary is deposited automatically.
This is one of the most common uses of both numbers.
Example 2: Receiving an IRS Tax Refund
David files his federal tax return and chooses direct deposit instead of receiving a paper check.
When completing his tax return, he provides:
- His routing number
- His account number
After the IRS approves his refund:
- The routing number identifies David’s bank.
- The account number identifies David’s checking account.
- The refund is deposited electronically.
Entering either number incorrectly could delay the refund until the banking information is corrected.
Example 3: Paying Monthly Bills
Sophia wants her electricity bill to be paid automatically every month.
She authorizes automatic payments through her utility company’s website.
The company asks for:
- Routing number
- Account number
Each month:
- The routing number identifies Sophia’s bank.
- The account number identifies her checking account.
- The payment is processed automatically.
This eliminates the need to remember monthly due dates.
Example 4: Linking a Savings Account
Michael has checking and savings accounts at two different banks.
He wants to transfer money between them without visiting a branch.
To link the accounts, the second bank requests:
- Routing number
- Account number
Once verified, Michael can transfer money electronically whenever he wants.
Example 5: Buying a Home
Jennifer is purchasing her first home.
Her title company requests a wire transfer before closing.
Jennifer contacts her bank because she isn’t sure whether the routing number used for direct deposit is also correct for wire transfers.
The bank confirms that wire transfers require different routing information.
By verifying the details before sending the payment, Jennifer avoids a costly mistake.
This is why you should never assume that every banking transaction uses the same routing number.
Can You Complete a Transaction Using Only One Number?
Usually, no.
A routing number alone doesn’t identify your personal account.
An account number alone doesn’t identify your financial institution.
Most electronic banking transactions require both.
Here’s a quick illustration.
| Banking Information Provided | Can the Payment Usually Be Completed? |
|---|---|
| Routing Number Only | No |
| Account Number Only | No |
| Routing Number + Account Number | Yes, in most cases |
| Incorrect Routing Number + Correct Account Number | Usually rejected or delayed |
| Correct Routing Number + Incorrect Account Number | Usually rejected or delayed |
This is why reviewing both numbers before submitting a payment is so important.
What Happens If You Enter the Wrong Routing Number?
Mistakes happen.
Fortunately, many routing number errors are caught before money leaves your account.
Depending on the situation, several outcomes are possible.
The Payment Is Rejected
If the routing number doesn’t correspond to a valid financial institution, the banking system will often reject the payment automatically.
You’ll usually receive an error message or be asked to correct your banking information.
The Payment Is Delayed
Sometimes the routing number belongs to a real bank but doesn’t match the transaction you’re attempting.
The payment may be delayed while additional verification takes place.
The Payment Is Returned
In some cases, the receiving bank cannot process the transaction and returns the funds to the sender.
Although your money is usually recoverable, the process can take several business days.
Additional Investigation May Be Required
If the payment cannot be processed automatically, your bank may need to investigate before releasing or returning the funds.
This is another reason to verify your banking information before sending important payments.
What Happens If You Enter the Wrong Account Number?
Entering an incorrect account number can also create problems.
Possible outcomes include:
- Immediate rejection
- Processing delays
- Returned payment
- Additional verification by the bank
Because account numbers identify individual customers, even one incorrect digit can prevent the payment from reaching the intended recipient.
Before approving any transaction, compare every digit carefully with your official banking records.
Security Tips for Protecting Your Banking Information
Although routing numbers are widely used, protecting your complete banking information is still important.
Follow these simple best practices.
Verify Before You Share
Only provide your routing number and account number to trusted employers, government agencies, financial institutions, or businesses you recognize.
If someone unexpectedly requests your banking information, confirm their identity before responding.
Watch for Phishing Attempts
Scammers frequently send emails or text messages pretending to represent banks.
They may ask you to “confirm” your banking details or click a fraudulent link.
Your bank will rarely request sensitive banking information through unsolicited email.
If you’re unsure, contact the bank directly using the phone number listed on its official website.
Use Secure Websites
Whenever you enter banking information online, make sure:
- The website uses HTTPS.
- You’re connected to a trusted internet connection.
- Your browser indicates the connection is secure.
Avoid entering banking information on public Wi-Fi whenever possible.
Monitor Your Accounts Regularly
Review your transactions frequently.
If you notice an unfamiliar payment, contact your bank immediately.
Early reporting greatly improves the chances of resolving unauthorized activity.
Before You Submit Any Banking Form
Whether you’re setting up payroll, authorizing automatic payments, or linking a financial app, take one final minute to review everything.
✔ Confirm the routing number.
✔ Confirm the account number.
✔ Verify the account type.
✔ Confirm the recipient or organization requesting the information.
✔ Review every digit carefully.
✔ Submit only after you’re confident everything is correct.
This simple checklist has helped countless people avoid rejected payments, delayed deposits, and unnecessary banking headaches.
Frequently Asked Questions About Routing Numbers and Account Numbers
If you’re still unsure about the difference between a routing number and an account number, you’re not alone. These are among the most frequently searched banking topics online. Below are answers to common questions that can help you avoid mistakes when sending or receiving money.
Is a Routing Number the Same as an Account Number?
No. A routing number identifies your financial institution, while an account number identifies your individual bank account. Both numbers work together during electronic transactions, but they perform completely different functions.
Which Number Comes First on a Check?
The routing number appears first on the left side of the check. It is followed by the account number, while the final group of numbers identifies the individual check.
Is a Routing Number Always Nine Digits?
Yes. Every ABA routing number used within the United States contains exactly nine digits. This standardized format helps payment systems identify financial institutions accurately.
Is an Account Number Always the Same Length?
No. Unlike routing numbers, account numbers vary in length from one bank to another. Depending on the financial institution, they may contain anywhere from eight to seventeen digits or even more.
Can Two People Have the Same Routing Number?
Yes. Routing numbers identify banks rather than customers. Thousands—or even millions—of customers at the same financial institution may share the same routing number.
Can Two People Have the Same Account Number?
No. Account numbers are unique within a financial institution. They are assigned to individual accounts so banks can distinguish one customer’s account from another.
Do Savings Accounts and Checking Accounts Have Different Account Numbers?
Yes. Even if both accounts belong to the same customer at the same bank, each account usually has its own unique account number.
Do Savings and Checking Accounts Share the Same Routing Number?
Often they do, but not always. Many banks use the same routing number for both checking and savings accounts within a region. However, the correct routing number depends on your bank and the type of transaction you’re completing.
Can I Use My Debit Card Number Instead of My Account Number?
No. A debit card number is completely different from a bank account number. Debit cards operate on card payment networks, while bank account numbers are used for direct deposits, ACH transfers, and many other banking transactions.
Is My Routing Number Printed on My Debit Card?
No. Debit cards do not display routing numbers. You’ll typically find your routing number through online banking, your mobile banking app, your checks, or your bank statement.
Is My Account Number Printed on My Debit Card?
Usually not. Your debit card contains a card number, which is different from your checking or savings account number.
Can I Receive Direct Deposit Without a Routing Number?
No. Employers and government agencies generally require both your routing number and your account number to send direct deposits electronically.
Can I Send Money Using Only My Account Number?
In most cases, no. Electronic bank transfers usually require both your routing number and your account number so the banking system knows both where the money should go and which account should receive it.
Which Number Is More Important?
Neither is more important. They serve different purposes. The routing number identifies the bank, while the account number identifies your specific account. Most banking transactions require both.
Can Routing Numbers Change?
Yes, although it doesn’t happen frequently. Banks may change routing numbers after mergers, acquisitions, or significant operational changes. If your routing number changes, your bank will usually notify you in advance.
Can Account Numbers Change?
Yes. Although less common, account numbers may change if you close your account, open a new one, convert account types, or if your bank requires new account numbering after a merger.
Can I Find Both Numbers Online?
Yes. Most banks display both routing numbers and account numbers through secure online banking and official mobile banking apps.
What Happens If I Enter the Wrong Routing Number?
The payment may be rejected, delayed, or returned. In some cases, additional investigation may be required before the transaction can be completed.
What Happens If I Enter the Wrong Account Number?
An incorrect account number may prevent the payment from reaching the intended recipient. Depending on the circumstances, the payment could be rejected, delayed, or returned by the receiving bank.
How Can I Double-Check My Banking Information?
The safest places to verify your routing number and account number include:
- Your online banking account
- Your bank’s official mobile app
- Your paper checks
- Your bank statement
- Your financial institution’s customer service
Avoid relying solely on unofficial websites because banking information can occasionally change.
Conclusion
Although routing numbers and account numbers often appear together, they serve two very different purposes within the U.S. banking system.
Your routing number identifies the financial institution responsible for processing the transaction, while your account number identifies your unique account at that institution. Together, they allow employers, businesses, government agencies, and banks to send money accurately and securely.
Whether you’re setting up direct deposit, paying bills automatically, linking a payment app, or transferring funds between accounts, understanding the difference between these two numbers can help you avoid common banking mistakes and unnecessary payment delays.
Before submitting any banking form, take a moment to verify both numbers using your bank’s official website, online banking portal, mobile app, or customer support. Spending a few extra seconds checking your information can save you days of frustration later.
If you’re continuing to build your banking knowledge, these guides can help you better understand how electronic payments work:
- What Is an ABA Routing Number? Meaning, Uses, Examples & How to Find Yours
- ACH Transfer vs. Wire Transfer: What’s the Difference and Which Should You Use?
- How to Find Your Bank Routing Number
- Why Do Banks Have Different Routing Numbers?
- 121000248 Routing Number: Which Bank Uses It and How to Avoid Costly Transfer Mistakes
By understanding how these banking tools work together, you’ll be better prepared to manage your money confidently, avoid costly errors, and complete financial transactions with ease.

