In this article packed with UpCrunch Reviews, we break down what real customers are actually saying before you commit your money or personal information. You’ll see patterns behind UpCrunch reviews complaints, insights pulled from UpCrunch reviews on Trustpilot, and feedback shared in UpCrunch reviews on Yelp. If you live in the USA and want to know the pros, cons, and red flags without marketing fluff, this overview sets the tone for an honest, practical review.
Table of Contents
What UpCrunch Is And What It Claims To Do
UpCrunch presents itself as a credit-focused financial service designed to help people improve their credit profile, gain access to better financial options, and understand where they stand before applying for loans or credit products. At its core, UpCrunch positions itself as a bridge between consumers with imperfect credit and lenders willing to work with them.
The promise is simple on the surface. UpCrunch claims to analyze your credit situation, match you with relevant financial offers, and in some cases help you take steps toward improving approval odds. For people who feel locked out of traditional banking options, that message is appealing.
Now that the positioning is clear, the next step is understanding who this service is actually meant for.
Who UpCrunch Is Really Designed For
UpCrunch is not built for people with excellent credit who already qualify for top-tier financial products. Its messaging, tools, and offers are clearly aimed at individuals with fair, poor, or rebuilding credit.
This includes people who have:
- Recent late payments
- High credit utilization
- Limited credit history
- Previous denials from traditional lenders
Many users come to UpCrunch after being rejected elsewhere and are looking for any path forward. That context matters when evaluating reviews because expectations shape satisfaction.
With that audience in mind, it’s important to examine what users say when things don’t go as expected.
Now that the target audience is clear, let’s look closely at the complaints that appear most often.
UpCrunch Reviews Complaints You Should Understand Clearly
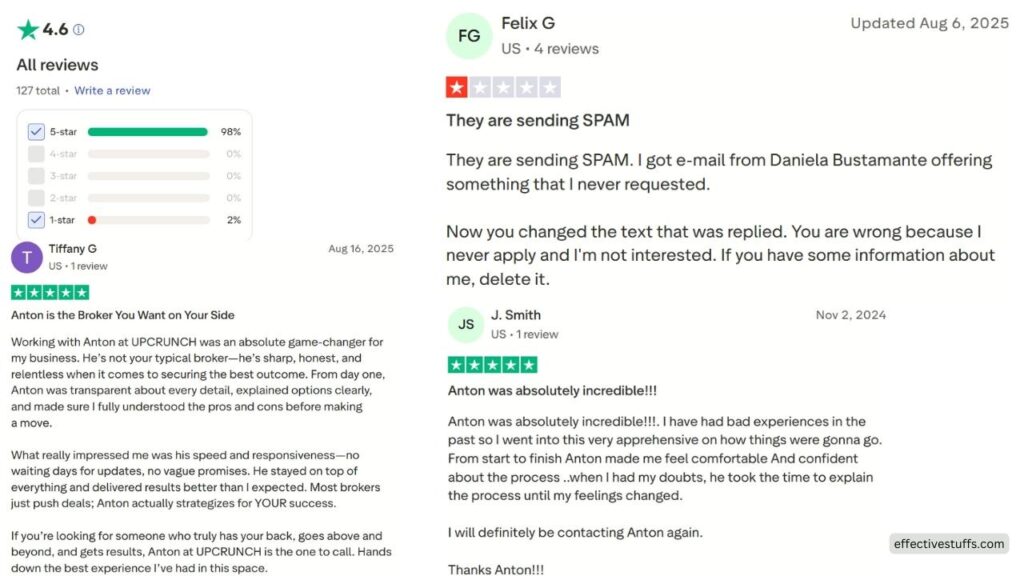
UpCrunch reviews complaints on Trustpilot are very limited and do not point to widespread service issues. Among the reviews available, only one reviewer raises a concern related to receiving an unsolicited email and expresses discomfort with being contacted without requesting information. This feedback centers on communication preferences rather than the quality of the service itself. Importantly, there are no recurring complaints about hidden fees, fraud, or unmet services. Overall, as at December 24th, 2025, Trustpilot feedback suggests that dissatisfaction is rare and tends to stem from isolated communication concerns rather than problems faced by users who actively engage with UpCrunch.
UpCrunch Reviews On Trustpilot As At Dec 24th, 2025
TrustPilot Reviews Breakdown Based On Verified Screenshots
TrustPilot feedback for UpCrunch shows a largely positive reputation, with a small number of sharp complaints that stand out clearly against the broader sentiment.
The overall rating sits high, with the vast majority of reviewers leaving five-star feedback and only a small percentage expressing strong dissatisfaction. This imbalance is important because it shows that negative experiences are present but not dominant.
Positive reviews consistently focus on the human element of the service. Several users describe working directly with an UpCrunch representative and highlight qualities such as clarity, honesty, speed, and consistent communication. Reviewers emphasize feeling guided rather than pressured, noting that options were explained in detail and that questions were addressed patiently. A recurring theme is responsiveness, with users mentioning quick follow-ups, regular updates, and a sense that their case was actively managed instead of ignored. For these users, the experience feels personal and results-driven, especially compared to past negative experiences with similar services.
On the negative side, the few one-star reviews concentrate almost entirely on unsolicited outreach. Some users report receiving emails offering services they did not request and express frustration after stating they were not interested. These complaints center on privacy concerns and communication boundaries rather than financial loss, deception, or service failure. The tone reflects irritation and distrust toward outreach practices, not accusations of fraud or misuse of funds.
When these reviews are viewed together, a clear pattern emerges. Users who intentionally engaged with UpCrunch and interacted directly with a representative tend to report strong satisfaction and positive outcomes. Users who felt contacted without initiating the process tend to respond negatively, even if no further interaction occurred.
In short, the TrustPilot screenshots suggest that UpCrunch delivers a strong experience for clients who actively seek its services, while its biggest weakness lies in how outreach is perceived by those who did not expect to be contacted.
After that level of bluntness, Yelp-style feedback adds another layer.
How UpCrunch Works Step By Step
UpCrunch generally follows a straightforward process.
First, users provide basic financial and credit-related information. This may include income range, credit range, and financial goals. The platform then analyzes this data to match users with relevant financial offers.
Next, users are shown potential products or pathways based on their profile. These may include credit cards, loans, or educational resources. UpCrunch itself does not issue credit or directly change credit reports.
Finally, users decide whether to pursue any of the presented options. At this stage, responsibility shifts entirely to the user.
Understanding this workflow helps explain both positive and negative reviews.
Now that functionality is clear, pricing and costs deserve attention.
UpCrunch Pricing And What You Are Really Paying For
One area competitors often gloss over is cost clarity. UpCrunch typically does not charge large upfront fees like traditional credit repair companies. Instead, its business model relies on partnerships and referrals.
For users, this means there is often no direct payment required to view matches or offers. However, the indirect cost is exposure to third-party products that may carry their own fees, interest rates, or conditions.
Some users feel misled when they realize the service itself is free but the recommended options are not necessarily favorable. Others appreciate that they can explore options without paying upfront.
The value depends entirely on whether the recommendations align with your financial situation.
That brings us to the question many readers care about most.
Is UpCrunch Legit Or A Red Flag
Based on user feedback patterns, UpCrunch does not show signs of being a scam. There are no widespread reports of missing funds, unauthorized charges, or identity misuse.
However, legitimacy does not automatically equal usefulness. UpCrunch is legitimate as a matching and informational platform, not as a credit repair service.
Red flags arise primarily when users misunderstand its role. If someone expects disputes, score manipulation, or guaranteed approvals, disappointment follows.
If approached as a discovery tool, the risk level is low.
Now let’s talk about what users actually gain when things go right.
Pros Of Using UpCrunch According To Real Users
Users who report positive experiences often mention:
- Fast access to potential options
- Reduced trial-and-error with lenders
- A clearer picture of what they qualify for
- No upfront payment requirement
For people with limited credit options, simply knowing what doors are open can be empowering.
These pros are practical, not transformational. That distinction matters.
Of course, no review is complete without addressing downsides clearly.
Cons Of Using UpCrunch You Should Not Ignore
Commonly reported downsides include:
- Lack of personalized coaching
- Marketing follow-ups that feel excessive
- Recommendations that mirror what users already found elsewhere
- No direct credit score improvement
These cons don’t make the platform harmful, but they limit its usefulness for certain users.
With pros and cons laid out, it helps to compare expectations against reality.
What UpCrunch Does Not Do
UpCrunch does not:
- Repair credit reports
- Remove negative items
- Negotiate with creditors
- Guarantee approvals
- Replace financial education
Many negative reviews stem from assuming one of these services was included.
Once expectations are corrected, the platform makes more sense.
At this point, readers often ask how UpCrunch compares to alternatives.
UpCrunch Compared To Traditional Credit Repair Services
| Feature | UpCrunch | Traditional Credit Repair Services |
|---|---|---|
| Primary Purpose | Matches users with potential financial options | Actively disputes and removes negative credit items |
| Credit Repair Actions | Does not dispute or modify credit reports | Sends disputes to credit bureaus and creditors |
| Upfront Fees | Usually no upfront cost | Often charges setup or monthly fees |
| Ongoing Monthly Fees | None for basic use | Common, even if no progress is made |
| Level Of Personal Guidance | Limited, mostly self-directed | Hands-on and managed for you |
| Speed Of Initial Use | Very fast, often minutes | Slower, requires onboarding and document review |
| Guarantees Results | No guarantees | No guaranteed results either |
| Best For | People exploring options with minimal risk | People wanting active credit dispute support |
| Risk Level | Low, informational and optional | Higher, due to ongoing fees and long timelines |
| User Responsibility | High, user must take action | Lower, service handles disputes |
Now let’s bring everything together with practical guidance.
Who Should Consider Using UpCrunch
UpCrunch may be useful if you:
- Want to explore options without upfront costs
- Prefer self-directed decision-making
- Have been denied elsewhere and want realistic alternatives
- Understand that it is not credit repair
It may not be suitable if you:
- Want hands-on credit fixing
- Need structured financial coaching
- Expect guaranteed outcomes
Matching the tool to the user is the key.
Before wrapping up, let’s address common questions people are actively searching for.
Frequently Asked Questions About UpCrunch Reviews
Is UpCrunch Legit Or A Scam
UpCrunch is generally considered legitimate in the sense that it operates openly and does what it claims at a basic level. It does not secretly take money or disappear after sign-up. However, it is not a credit repair service. Most scam accusations come from users expecting guaranteed results or active credit fixing, which UpCrunch does not provide.
What Does UpCrunch Actually Do
UpCrunch analyzes basic financial and credit-related information and matches users with potential financial offers or options. It does not issue credit, approve loans, or change credit reports. Think of it as a discovery and matching platform rather than a service that directly improves your credit or negotiates on your behalf.
Does UpCrunch Improve Your Credit Score
UpCrunch does not directly improve credit scores. Any improvement depends on what actions you take after using the platform, such as applying for appropriate products or changing financial habits. The platform itself only provides information and potential pathways, not active score manipulation or dispute services.
Why Are There So Many UpCrunch Complaints Online
Most complaints stem from mismatched expectations. Some users believe UpCrunch will repair credit or guarantee approvals. When that does not happen, frustration follows. Complaints are rarely about missing money or fraud and more often about usefulness, clarity, and perceived value.
Is UpCrunch Free To Use
UpCrunch is usually free to access and does not require upfront payment from users. However, the products or services it recommends may have their own fees, interest rates, or conditions. The platform itself earns money through partnerships rather than direct user charges.
Does UpCrunch Run A Credit Check
UpCrunch does not typically perform a hard credit check. However, if you choose to apply for a product through a third party after using the platform, that lender may run its own credit inquiry. Understanding this distinction helps prevent surprises.
Will Using UpCrunch Hurt Your Credit
Using UpCrunch alone does not hurt your credit. Credit impact only occurs if you apply for financial products that involve credit checks. Being selective about applications helps protect your score.
Why Does UpCrunch Ask For Personal Information
The platform uses personal and financial details to generate relevant matches. Without basic information, it cannot suggest appropriate options. Users uncomfortable with data sharing should review what they provide and understand that marketing follow-ups may occur.
Does UpCrunch Guarantee Loan Or Card Approval
No. UpCrunch does not guarantee approval for any financial product. All final decisions are made by third-party lenders. Any platform claiming guaranteed approval should be approached cautiously.
Is UpCrunch The Same As Credit Repair
No. Credit repair involves disputing negative items and communicating with creditors or bureaus. UpCrunch does none of that. It provides information and potential options but leaves all action steps to the user.
Why Do People Expect More From UpCrunch
Marketing language and desperation often fuel unrealistic expectations. People struggling with credit want fast solutions. When UpCrunch delivers information instead of transformation, disappointment can occur even though the platform did what it was designed to do.
Are UpCrunch Reviews On Reddit Trustworthy
Reddit-style discussions tend to be blunt and experience-based. While opinions vary, patterns across posts are useful. Most users describe what they expected, what they got, and whether it met their needs, which helps others decide realistically.
What Do Positive UpCrunch Reviews Have In Common
Positive reviews usually come from users who understood UpCrunch as a tool for exploration. These users value seeing realistic options, avoiding repeated denials elsewhere, and gaining clarity without paying upfront.
What Do Negative UpCrunch Reviews Have In Common
Negative reviews often come from users expecting direct credit repair, guaranteed approvals, or personalized coaching. When those expectations are not met, frustration follows, even though those services were never explicitly offered.
Does UpCrunch Contact You After Sign-Up
Many users report receiving follow-up emails or offers after using UpCrunch. This is part of its matching and partnership model. Those who prefer minimal communication may find this aspect annoying.
Can You Opt Out Of UpCrunch Emails
Most platforms allow users to unsubscribe from marketing emails. Doing so early helps reduce inbox clutter. Reviewing preferences after sign-up is a smart step.
Is UpCrunch Worth Trying If You Have Bad Credit
It can be worth trying if you want to see potential options without paying upfront. However, it should not replace education, budgeting, or long-term credit improvement strategies.
Does UpCrunch Work For Good Credit
People with strong credit may find limited value because they already qualify for better options elsewhere. UpCrunch is clearly more geared toward those with fair or poor credit profiles.
Is UpCrunch Safe With Personal Data
There are no widespread reports of identity theft tied to UpCrunch. Still, users should always be cautious with personal information and understand how their data may be used for matching and marketing.
How Long Does It Take To Use UpCrunch
The process is usually quick. Many users complete the initial steps in minutes. The time investment is low, which is one of the platform’s main advantages.
Does UpCrunch Offer Customer Support
Support experiences vary. Some users report basic assistance, while others feel support is limited. The platform is not designed to provide ongoing one-on-one guidance.
Can UpCrunch Help You Get Out Of Debt
UpCrunch does not directly reduce debt. It may show options that could help manage debt, but results depend on what actions you take afterward.
Is UpCrunch Better Than Doing Nothing
For some users, yes. Seeing realistic options can prevent repeated denials and help guide next steps. For others, it adds little beyond what independent research could achieve.
Does UpCrunch Replace Financial Education
No. It does not teach budgeting, credit mechanics, or long-term planning in depth. Users still need to educate themselves to make good decisions.
Why Do Some Users Feel Misled By UpCrunch
Misunderstanding the platform’s role is the main cause. When people assume it actively fixes credit or negotiates outcomes, disappointment follows.
Is UpCrunch Transparent About What It Does
The platform generally explains its function, but users may skim or assume more than what is stated. Reading descriptions carefully helps align expectations.
Can UpCrunch Help With Loan Denials
UpCrunch may show alternative options after denials, which can save time. However, it does not change lender decisions or approval criteria.
Does UpCrunch Charge Monthly Fees
UpCrunch itself typically does not charge monthly fees. Costs may come from third-party products chosen after using the platform.
Is UpCrunch Good For Beginners
Beginners may find value in seeing options laid out simply. However, those who need structured education may still feel lost without additional guidance.
Can UpCrunch Help With Credit Cards
It may show credit card options based on your profile. Approval and terms depend entirely on the issuing company.
Does UpCrunch Fix Errors On Credit Reports
No. Users must dispute errors themselves or use dedicated credit repair services for that purpose.
Why Does UpCrunch Feel Like Advertising To Some Users
Because it connects users to partner offers. For some, this feels helpful. For others, it feels like marketing rather than assistance.
Is UpCrunch Better Than Traditional Credit Repair
They serve different purposes. UpCrunch is informational and low-risk. Credit repair is hands-on but often costs more. Choosing depends on what help you actually need.
Can UpCrunch Help After Bankruptcy
It may show options for people rebuilding after bankruptcy, but results depend on timing, income, and individual circumstances.
Does UpCrunch Offer Guaranteed Results
No. Any improvement depends on follow-through and external factors beyond the platform’s control.
Is UpCrunch Useful Short-Term Or Long-Term
It is mainly useful short-term as a snapshot and option-finding tool. Long-term credit improvement requires ongoing effort beyond the platform.
Why Do Reviews Vary So Much
Because expectations, credit situations, and goals differ widely. The same experience can feel helpful to one user and useless to another.
Should You Rely Only On UpCrunch
No. It should be one tool among many. Relying on a single platform limits understanding and progress.
Does UpCrunch Replace A Financial Advisor
No. It does not offer personalized financial planning or long-term strategy advice.
Can UpCrunch Help You Understand Your Options
Yes, at a basic level. It can clarify what types of products might be available based on your situation.
Is UpCrunch Worth It For No Credit
It may help show starter options, but those with no credit should also explore educational resources and beginner-focused products.
Does UpCrunch Push Specific Products
Recommendations are influenced by partnerships. This does not mean options are bad, but it does mean users should evaluate offers independently.
Can You Use UpCrunch More Than Once
Yes. Some users revisit the platform as their financial situation changes to see updated options.
Is UpCrunch A One-Stop Solution
No. It is a starting point, not a complete financial solution.
What Is The Biggest Red Flag With UpCrunch
The biggest red flag is assuming it does more than it actually does. Clear expectations prevent most negative experiences.
What Is The Biggest Benefit Of UpCrunch
The biggest benefit is low-risk access to potential options without upfront cost, especially for people unsure where they stand.
Should You Try UpCrunch Or Skip It
Trying it can make sense if you understand its role. Skipping it may be better if you want hands-on credit repair or personalized coaching.
Conclusion: Final Verdict On UpCrunch Reviews
UpCrunch sits in a gray area that confuses many users. It is neither a scam nor a magic solution. It is a legitimate platform designed to inform, match, and guide—not to fix.
Most negative reviews come from expecting transformation instead of information. Most positive reviews come from users who understood its role from the start.
If you approach UpCrunch as a tool, not a promise, it can be useful. If you expect it to change your financial life on its own, disappointment is likely.